 By Henk-Jan Grijpstra
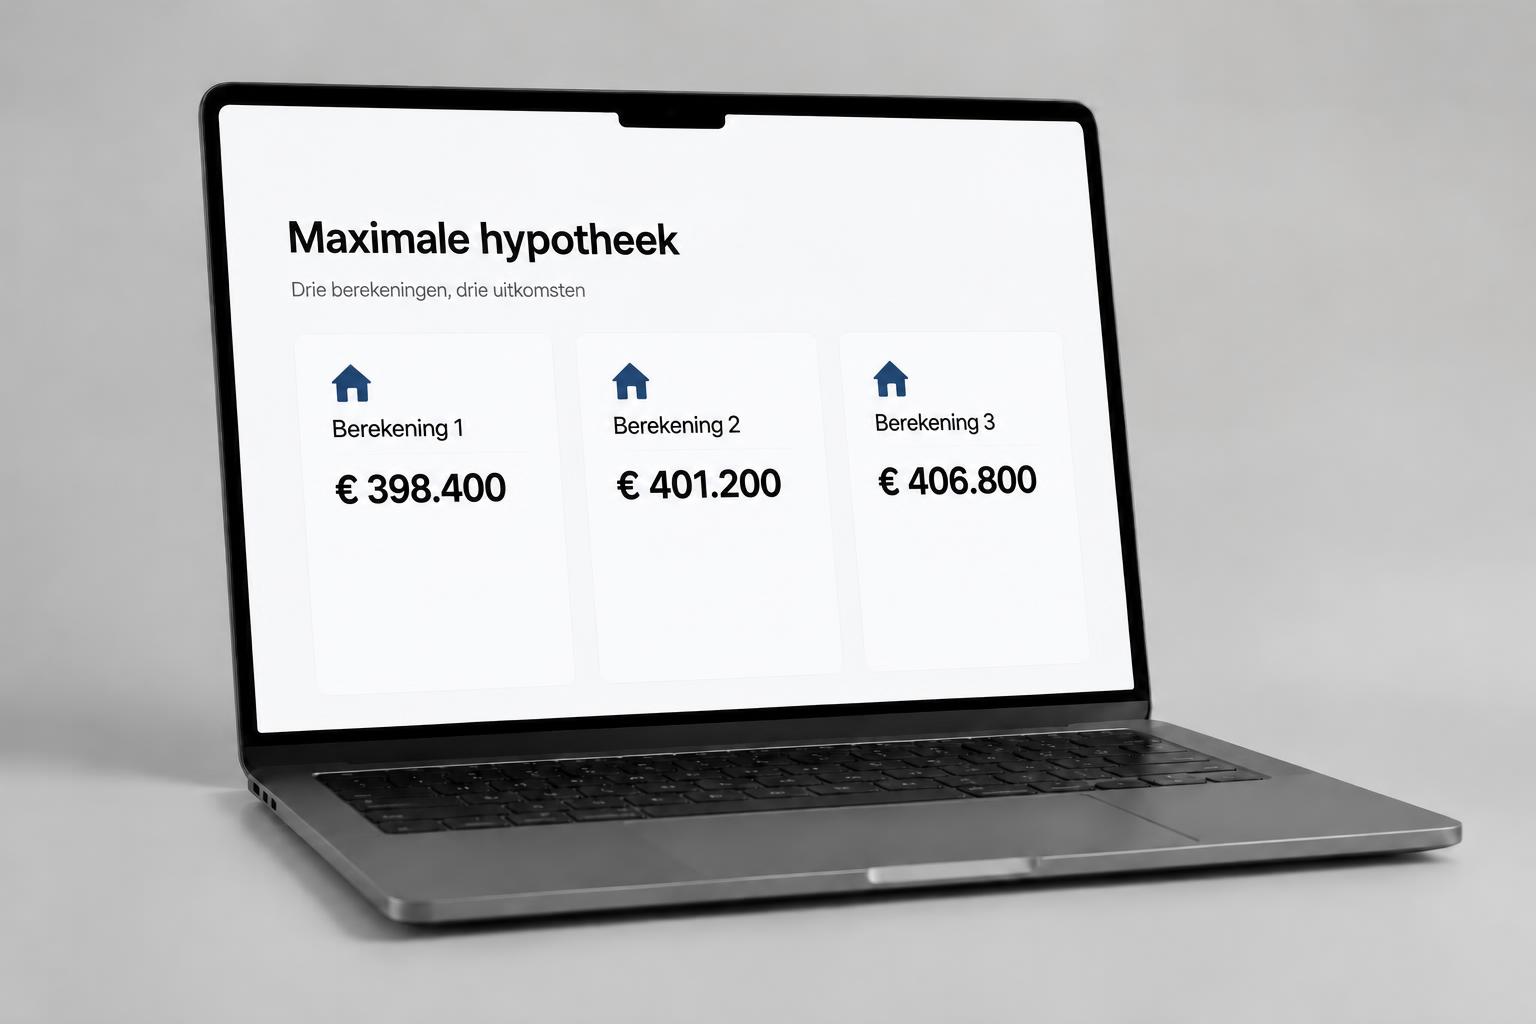
Have you calculated your maximum mortgage with different online calculators? Then you may well have ended up with three different outcomes. How is that possible?
One important reason is that not every tool uses the same assumptions. Some tools also show you the highest possible loan amount by default. But how is your maximum mortgage actually determined?
How is your maximum mortgage calculated?
Your maximum mortgage is determined by your (joint) income, the so-called assessment income, and the mortgage rate, among other things.
Based on these figures, it is calculated what share of your income you may spend on housing costs at most. This percentage is called the housing cost ratio (woonquote).
And here's something remarkable: the higher your income, the larger the percentage of it you may spend on mortgage costs.
That may sound odd, but there is a logic behind it.
Imagine this: someone earning €50,000 a year eats two potatoes for dinner. Someone earning €100,000 probably still eats two potatoes. Basic needs don't double when your income doubles. As a result, with a higher income you relatively have more left over to spend on housing.
The housing cost ratio takes this principle into account.
Why does the mortgage rate matter so much?
Besides your income, the mortgage rate plays an important role. What many people don't know is that the housing cost ratio is not the same at every rate.
For this calculation, rates are divided into steps of 0.5 percentage point. For example:
- 4.01% up to and including 4.50%
- 4.51% up to and including 5.00%
That can make quite a difference. If your rate falls just under the boundary (for example 4.49%), your maximum mortgage can turn out higher than when your rate lands just above it.
A rate of 4.50% and 4.51% barely seems different. Yet the difference in maximum mortgage can easily be €10,000 or more.
That's because a different rate band comes with a different housing cost ratio. So it's not only the size of your monthly payments that changes; the percentage of your income you're allowed to spend can change too.
Which mortgage calculation can you trust?
So determining your maximum mortgage is less straightforward than entering your income into a tool. It depends on several factors, and sometimes a small difference in assumptions already has a considerable effect on the outcome.
Curious how much you can really borrow?
At TdHG we look at your personal situation and calculate your options. Not just based on a quick online indication, but with the right assumptions and a comparison of the options across different lenders.
Book an appointment and we'll work it out precisely for you.